The Scariest Thing About Halloween Isn’t the Costumes. It’s Your Liability Limits.
Trick-or-treaters on your steps, your dog at the door, kids in the street, and a party in the backyard. Here’s who pays when Halloween goes wrong in Kansas, and how to make sure it isn’t you.
Halloween is one of the best nights of the year in Wichita neighborhoods. It’s also the one night you invite dozens of strangers, most of them small children in the dark, to walk up to your front door.
Most nights go fine. But when something does go wrong, the questions come fast. Am I liable? Does my policy cover this? Do I have enough? Let’s walk through the five situations we get asked about most.
1. Who pays if a trick-or-treater gets hurt on your porch?
An injury on your property doesn’t automatically make you liable. The question is usually whether you took reasonable care to keep your property safe. The most common problems are easy to spot ahead of time: a broken or loose step, a dark walkway, or an extension cord stretched across the yard to power the decorations.
Fire is the other risk. According to the National Fire Protection Association, decorations start an average of about 835 home fires a year. Nearly half happen because decorations were too close to a heat source, and about a third are started by candles.
Marc’s Tip: Go Battery-Powered
Put a battery candle in the jack-o’-lantern, keep cords out of the walking path, and turn on every porch and walkway light you have. Ten minutes of prep removes most of the risk.
The two coverages that matter here
Personal Liability
Part of your homeowners or renters policy. It helps pay if someone is hurt on your property and you’re found responsible, including legal costs if they sue.
Medical Payments
Pays a guest’s smaller medical bills no matter who was at fault. It can take care of a scraped knee or a sprained ankle before it turns into a lawsuit.
2. Your dog plus 100 doorbell rings
Even the friendliest dog can react badly to masks, costumes, screaming kids and a doorbell that won’t stop. And dog-related claims are climbing fast.
28,450 claims
Dog-related injury claims nationwide in 2025, up 25.6% from the year before, according to the Insurance Information Institute.
$65,450 per claim
The average cost of a dog-related claim in 2025. That’s nearly double what it was a decade ago.
How Kansas handles dog bites
Kansas doesn’t have a dog-bite statute. Instead, courts generally follow what’s called the “one-bite rule.” An owner can be held liable if they knew, or should have known, the dog could be dangerous. Ordinary negligence, like letting a dog run loose, can also make you responsible. That’s different from Missouri, where owners are generally held strictly liable.
The one-bite rule only helps once
After your dog bites or seriously threatens someone, you’re now the owner who knew. Any future incident gets much harder to defend.
The easy fix: crate your dog or put it in a back room for the evening. Also check your policy. Some carriers limit or exclude liability for certain breeds or for dogs with a bite history, and the rules vary from carrier to carrier. If you’re not sure where yours stands, call us.
3. Halloween night is the most dangerous night to be on foot
A study of 42 years of data published in JAMA Pediatrics found pedestrian deaths were 43% more likely on Halloween evening than on comparable nights. For kids ages 4 to 8, the risk was 10 times higher, with the danger peaking around 6 p.m.
It’s a growing problem close to home, too. Kansas pedestrian deaths more than doubled between 2019 and 2022, according to the Governors Highway Safety Association. On Halloween, slow down in neighborhoods, put the phone away and watch for street closures around trunk-or-treat events.
The insurance math nobody wants to do
If you hit a child and carry the Kansas minimum of $25,000 per person in bodily injury liability, that’s all your policy will pay for their injuries. Hospital stays, surgery and long-term care can run far past that, and you’re personally responsible for the rest.We break down Kansas auto minimums in our post on the most expensive sentence in auto insurance.
4. Hosting the Halloween party in Kansas
Kansas doesn’t have a dram shop law, the kind of law that holds whoever served the alcohol responsible for what a drunk guest does afterward. Kansas courts have also declined to hold social hosts civilly responsible for adult guests who drink and later hurt someone.
Teens are a different story
Under Kansas law (K.S.A. 21-5608), intentionally or recklessly letting minors drink on your property is a Class A misdemeanor. That carries a minimum $1,000 fine and up to a year in jail. Because the law covers reckless behavior, not just intentional, “I didn’t know they brought it” may not protect you.
And regular premises liability still applies no matter what anyone was drinking. A guest who falls down your stairs or gets burned by the fire pit is a liability claim.
Keep it simple
If teens are coming over, keep the alcohol locked up and the adults paying attention. Light the stairs and walkways, keep a safe zone around the fire pit, and have a plan to get anyone who’s been drinking home safely.
5. Eggs, stolen inflatables and the one fix for the big stuff
Insurer claims data shows Halloween is one of the peak times of year for vandalism and theft claims. Here’s generally how your homeowners policy sorts it out:
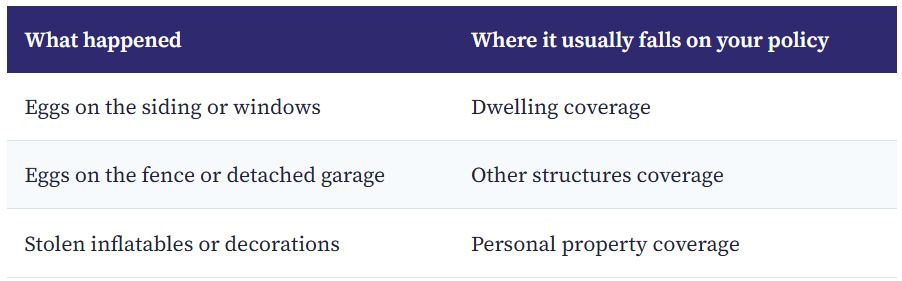
Here’s the catch: egging is usually covered, but the cleanup rarely costs more than your deductible. In most cases, filing a claim isn’t worth it.
“Pressure-wash the eggs. Call me about the lawsuit.”
Marc Shook, Shook Insurance Agency
The real Halloween treat: an umbrella policy
A dog bite, a hurt trick-or-treater, or a child hit in the street can each run well past the limits on a standard home or auto policy. That’s where an umbrella policy comes in. It’s extra liability coverage that sits on top of your home and auto policies and kicks in when their limits run out.
A $1 million umbrella often costs a few hundred dollars a year for a typical household. Umbrella policies usually require certain minimum liability limits on your home and auto first, so it’s worth reviewing them together.
Check your limits before October 31
Not sure if your liability limits would hold up after a bad night? Give us a call. We’ll review your home, renters, and auto liability together and show you what an umbrella would cost, so you can enjoy Halloween without the scary part.
This post is for general educational purposes and does not constitute legal or insurance advice. Coverage varies by policy and carrier. Legal information is general in nature; consult an attorney about your specific situation. Sources: Insurance Information Institute dog-related injury claims data, 2025; JAMA Pediatrics, Pedestrian Fatalities Associated With Halloween; Governors Highway Safety Association; National Fire Protection Association; K.S.A. 21-5608; Kansas Insurance Department.